East Africa’s startup scene has stopped being a story about potential. It is now a story about revenue. In 2024, startups across the region raised over $800 million in venture capital, with Nairobi and Kigali taking the largest shares — and the businesses attracting that money are solving unglamorous, essential problems.
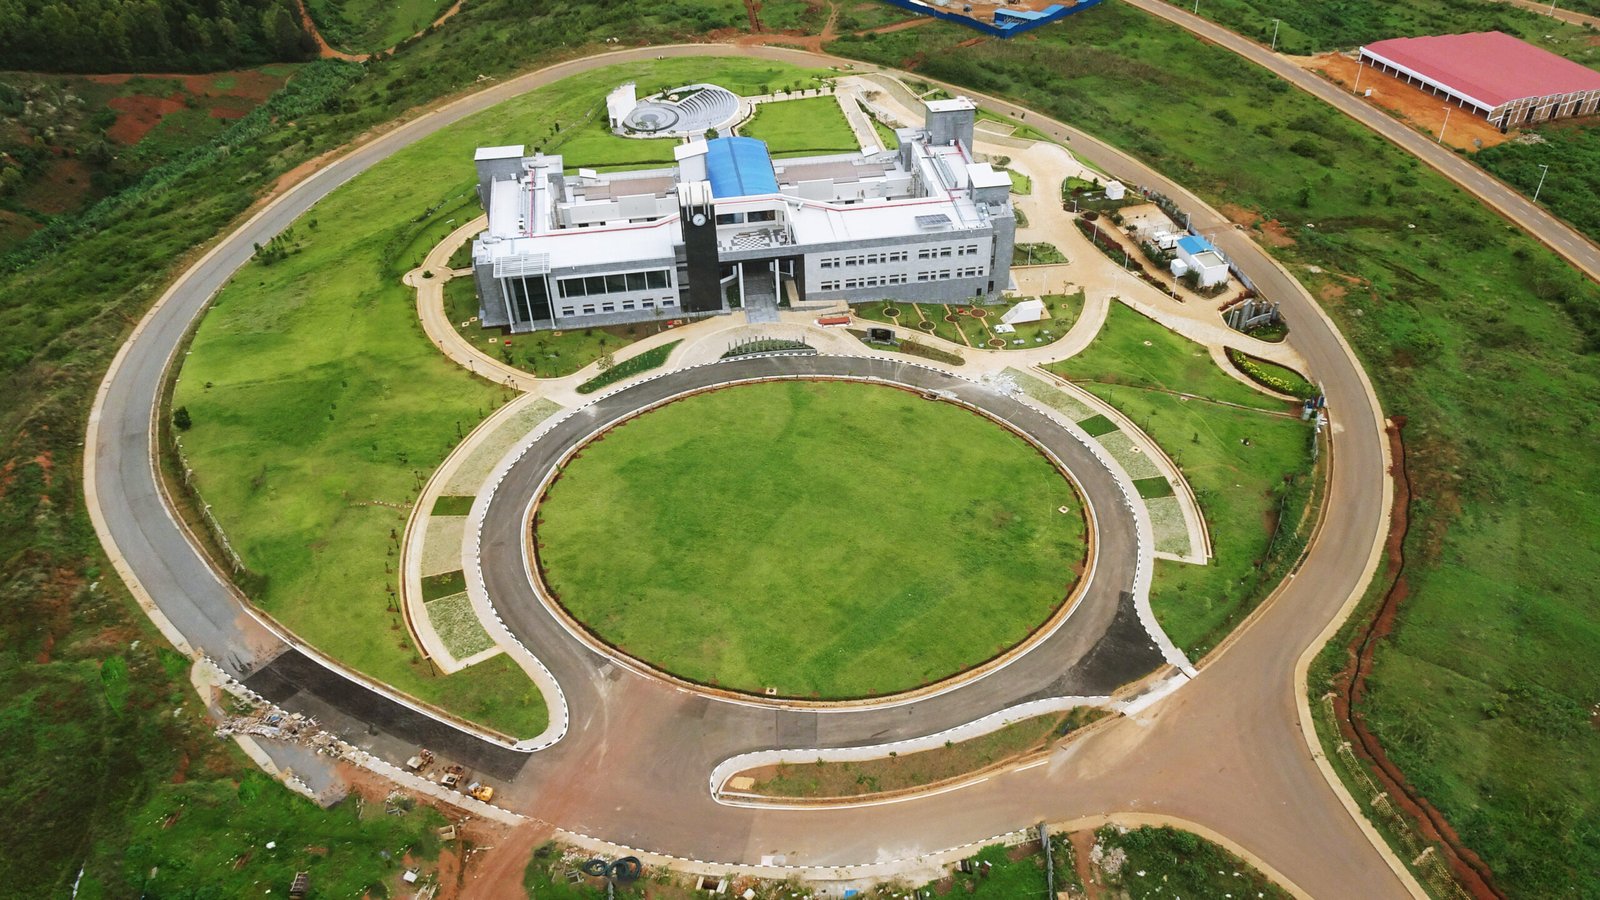
Kigali’s role has grown sharply. The city’s technology district, anchored by Kigali Innovation City and a cluster of incubators, now hosts dozens of companies working across fintech, agritech, health, logistics, and renewable energy. Government policy has helped: streamlined company registration, a sandbox for financial innovation, and visa rules designed to attract engineers.
Where the money is going
Fintech still dominates. Mobile money interoperability, lending platforms, and cross-border payments attract the biggest cheques because the market is enormous and the margins are proven. Zola Electric, which provides affordable solar power to off-grid households, and YAP, a digital banking platform serving millions of unbanked customers, are among the names that have scaled beyond a single market.
Put your brand in front of 12,000 engaged readers
Display · Newsletter · Sponsored features
Agritech is the second wave. Platforms that link smallholder farmers to buyers, provide input financing, and deliver weather intelligence are finding customers fast in economies where agriculture employs the majority of the workforce. Health tech, logistics, and climate tech follow close behind.
The talent here is extraordinary. What’s different now is that founders are solving real problems — not just copying Silicon Valley models.
What changed
Three things. First, infrastructure: cheap smartphones, widespread 4G, and mobile money rails that make digital products viable at scale. Second, talent: a generation of engineers and operators who trained locally or returned from abroad, plus programmes like Carnegie Mellon University Africa’s Kigali campus feeding the pipeline. Third, capital discipline: investors are funding businesses with clear unit economics rather than growth at any cost.
- Payments and lending — the largest share of funding, driven by mobile money penetration
- Agritech — fastest-growing category, tied to export crops and food security
- Climate and energy — solar, clean cooking, and electric mobility attracting development finance
- Health and logistics — smaller rounds, strong public-sector partnerships
The hard parts
Later-stage capital remains thin. A company that proves its model in Kigali often struggles to raise the $5–20 million needed to expand into Uganda, Tanzania, and the DRC. Regulatory fragmentation means rebuilding compliance in every market. And experienced operators — people who have scaled a company before — are still scarce.
Currency risk and inflation add pressure, particularly for businesses importing hardware. Several promising companies have relocated headquarters to Nairobi or Lagos in search of deeper pools of capital, a trend Rwandan policymakers are working to reverse with new fund-of-funds structures and tax incentives.
What to watch next
The clearest signal will be exits. As acquisition activity picks up — regional banks buying fintechs, logistics groups absorbing delivery startups — founders and their early employees gain the capital and confidence to build again. A functioning exit market is what turns a startup scene into an industry.
East Africa is closer to that threshold than at any point in its history. The companies being built today are less flashy than the first generation — and considerably more likely to last.